
Why investment diversification matters in an uncertain world
Geopolitical tensions, trade disputes and energy shocks can quickly affect markets.
Diversification enables investors to avoid putting too much of their financial future at risk. Investing always involves uncertainty, but the geopolitical backdrop has become increasingly difficult to predict. Conflicts in the Middle East and Ukraine, tensions between major economies and changing trade policies can affect energy prices, inflation, currencies, company profits and financial markets around the world.
What I wish I’d known before I retired
Nearly a third of retirees say their standard of living is worse than before retirement.
Retirement is often imagined as a chance to relax, travel and spend more time with family and on hobbies. However, new research suggests the reality can be more financially demanding than expected. Nearly a third (31%) of retirees say their standard of living is now worse than before they retired, compared with 20% who say it has improved[1].
Upcoming changes raise concerns among savers
More than one in five adults report a decline in pension confidence.
The upcoming changes to how pensions are treated for Inheritance Tax (IHT) from 6 April 2027 appear to be having a wider impact on pension confidence, despite most adults being unaffected. New research finds that 49% of adults say their confidence is unchanged, while 22% say it has fallen since the rules were announced in the 2024 Autumn Budget[1].
Understanding pension drawdown
Taking control of your pension income means considering the tax consequences.
Pension drawdown enables you to take money from a defined contribution pension while keeping the rest invested. Rather than receiving a fixed income, you decide how much to withdraw and when, giving you flexibility to adjust your income as your circumstances change.
There are several ways to access a defined contribution pension. You could take your tax-free lump sum and leave the rest invested in drawdown, take smaller withdrawals
The true cost of raising a child in 2026
From childcare and essentials to education and everyday expenses.
Raising a child is a major financial commitment, with costs beginning long before school age. The latest figures from the Child Poverty Action Group (CPAG) estimate the cost of raising a child from birth to 18 at £250,000 for a couple and £290,000 for a lone parent[1].
Its 2025 ‘Cost of a Child’ report also found that families are further from achieving a decent standard of living than at any point
Securing income in retirement
Building financial security for later life.
Retirement no longer has to mean simply buying an annuity and receiving a fixed income for life. Since pension freedoms were introduced, people have had greater control over how and when they access their pension savings.
However, greater choice can complicate retirement planning. If you want the security of knowing that essential bills will be covered, establishing a reliable income strategy should be a key part of your planning.
Reconsidering how to use pension savings and pass wealth to the next generation
It is increasingly important to consider pensions alongside other assets when planning.
For families with substantial pension savings, the rules are changing. From 6 April 2027, most unused pension funds and pension death benefits will form part of an estate’s value for Inheritance Tax (IHT) purposes. The change could prompt people to reconsider how they use their pension savings and pass wealth to the next generation.
Protecting your loved ones with a Will
Providing greater control over your assets and protection for those who matter.
A Will can help you put your financial affairs in order, plan your inheritance and ensure your wishes are known. Despite this, many people delay making one, often assuming it can be dealt with later. Without a Will, the law determines how your estate is distributed.
This may not reflect your wishes and could create further complications for those you leave behind. Writing a Will provides greater certainty,
Giving money or valuable possessions to loved ones
54% of over-55s have no record of gifts given in the previous seven years.
Giving money or valuable possessions to loved ones can be a generous way to provide support, but failing to keep track of those gifts could leave families facing an Inheritance Tax (IHT) headache later. New research shows that 54% of over-55s who have given a financial gift in the past seven years have kept no record of it[1].
The research found that only 13% have recorded

Five questions to ask yourself before retirement
Are you doing enough today to give yourself the freedom and choices you want tomorrow?
Retirement should be something to look forward to, not a source of financial anxiety. For many people, retirement can seem comfortably distant until, suddenly, it is not. Years of working, saving and paying into pensions can create the sense that everything will somehow fall into place.
The reality is that, without a clear plan, you could reach retirement and realise that the lifestyle you imagined
Could looking after grandchildren add to your State Pension?
A little-known National Insurance credit could reward you and give you a financial boost.
Providing regular childcare for grandchildren could do more than help your family. It could also help protect your State Pension entitlement through National Insurance credits. Grandparents who spend their time caring for grandchildren may be able to claim Specified Adult Childcare credits.
These are Class 3 National Insurance credits that can fill gaps in your National Insurance record and, in turn, build entitlement to the State
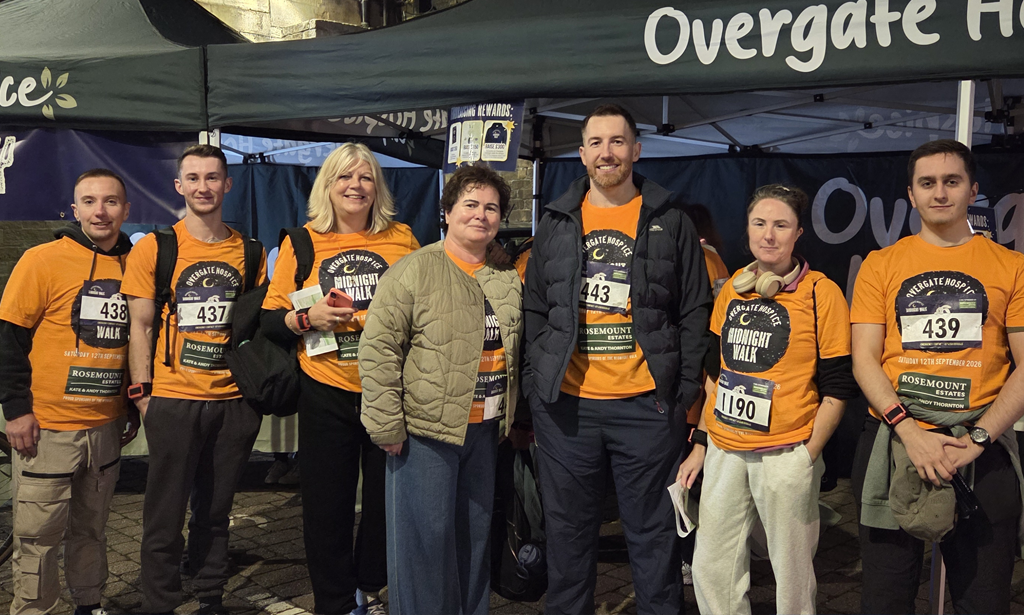
The Investing For Tomorrow team raise over £2,000 for Overgate Hospice
We did it! Toby and the team completed the 10-mile midnight challenge walk, raising £2,145 for Overgate Hospice who provides care for patients in Calderdale who have a terminal illness or a long term condition that cannot be cured.