Annuities offer certainty

An annuity is one of the most straightforward ways to secure a guaranteed retirement income. In exchange for some or all of your pension savings, an insurer pays you a regular income, typically for the rest of your life.

The rate offered depends on factors such as your age, pension size, prevailing interest rates and, in some cases, your health and lifestyle. You can usually take your pension commencement lump sum separately, subject to the relevant tax rules.

Types of annuity

There are several types of annuity to consider. A level annuity pays a fixed income, while an escalating or inflation-linked annuity is designed to increase over time to help protect your spending power.

You may also be able to choose a joint-life annuity, which continues to pay an income to your spouse or partner after your death. These additional protections can provide greater security for your family, but they will generally reduce the initial income.

Don’t overlook your State Pension

The State Pension can provide an important foundation for retirement income. For 2026/27, the full new State Pension is £241.30 per week, equivalent to around £12,548 per year. The amount you receive depends on your National Insurance record. The State Pension age is currently 66 and a number of months, as it gradually rises from age 66 to 67 between April 2026 and April 2028. It may increase to 68 by 2046 or potentially earlier.

Checking your State Pension forecast can help you determine how much guaranteed income you can expect and when it will start. This can then be factored into your wider retirement income strategy.

Drawdown offers flexibility

Pension drawdown lets you keep your pension invested while taking an income as and when required. This can be useful if your spending varies throughout retirement, but unlike an annuity, the income is not guaranteed. Your pension remains exposed to investment markets, so poor performance combined with high withdrawals could increase the risk of your savings running down too quickly.

Withdrawals are generally subject to Income Tax, although you can usually take up to 25% of your pension as tax-free cash, subject to the relevant limits. In England, Wales and Northern Ireland, the standard Personal Allowance for 2026/27 is £12,570, and income is generally taxed at 20%, 40% or 45%, depending on your total taxable income. The Personal Allowance begins to taper once adjusted net income exceeds £100,000.

A blended approach

You do not necessarily have to choose between an annuity and a drawdown. Combining the two can provide a balance between certainty and flexibility.

For example, you could use part of your pension to secure sufficient guaranteed income to cover essential spending, while keeping the remainder invested to fund discretionary spending or cover unexpected costs.

Consider your wider finances

Your pension is only one part of the picture. Savings, investments and rental income may also contribute to your retirement income, but they do not necessarily offer the same guarantees as an annuity or the State Pension.

Tax planning is also important. For 2026/27, the standard pension annual allowance is £60,000, or 100% of earnings, whichever is lower. For high earners, this can be reduced by £1 for every £2 of adjusted income above £260,000, subject to the applicable thresholds and the minimum allowance. The Money Purchase Annual Allowance is £10,000 for those who have flexibly accessed a defined contribution pension.

Get advice before making a decision

Deciding how to turn pension savings into retirement income can affect your financial security for many years. An annuity can provide a guaranteed income for life but is generally irreversible once purchased, making it important to understand the available options before committing.

Drawdown offers greater control but requires careful management of investment risk and withdrawals. Professional financial advice will help you assess the different approaches, consider the tax implications and develop a strategy appropriate to your circumstances and retirement goals.

This article does not constitute tax, legal or financial advice and should not be relied upon as such. For guidance, seek professional advice. A pension is a long-term investment not normally accessible until age 55 (57 from April 2028, unless the plan has a protected pension age). The value of your investments (and any income from them) can go up or down, which would affect the level of pension benefits available. Investments can rise or fall in value, and you may receive back less than you invested.

Annuities are long-term, complex financial instruments that may not be suitable for all investors. The information in this material is for informational purposes only and does not constitute financial advice. All investments carry risk, and annuities are no exception. The performance of an annuity is not guaranteed and can be affected by market conditions and other factors. It is essential to carefully consider your financial situation, investment objectives, and the product’s fees and restrictions before purchasing an annuity.

The tax implications of pension withdrawals will depend on your individual circumstances. Tax thresholds, percentage rates and tax legislation may change in subsequent finance acts.
While most estates are still expected to have no Inheritance Tax liability, the reforms mean some families could face a higher tax bill. This makes it increasingly important to consider pensions alongside other assets when planning for long-term financial and estate matters.

Consider gifting during your lifetime

One potential approach is to consider whether some wealth could be passed on during your lifetime rather than retained within your estate. This could include making contributions to a loved one’s pension, helping them build their own retirement savings while potentially reducing the value of your estate.

However, a payment into someone else’s pension is generally treated as a gift for Inheritance Tax purposes, so the rules on lifetime gifts need careful consideration. The £3,000 annual exemption can be used for qualifying gifts, and regular gifts from surplus income may also be exempt if certain conditions are met.

Understand the seven-year rule

Larger gifts that do not qualify for an exemption may fall outside your estate if you survive for seven years after making them. These are known as ‘potentially exempt transfers’. If you die within seven years, the gift may be relevant for Inheritance Tax calculations, depending on the circumstances and the value of other gifts made.

This means gifting can be a long-term strategy rather than a quick way to reduce a potential tax bill. You also need to consider whether you can afford to give money away without compromising your retirement income or financial security.

Review how your pension is used

The forthcoming changes could also prompt some people to reconsider whether to leave significant pension wealth untouched. Depending on your circumstances, drawing an appropriate level of income in retirement and using other assets strategically could affect the eventual value of your estate.

However, withdrawing money solely to avoid Inheritance Tax may not always be the right decision. Pension withdrawals can have Income Tax implications, and taking too much too soon could reduce the funds available to support you later in life.

Plan for the next generation

For some families, contributing to a child’s or grandchild’s pension could be a way to provide financial support while encouraging long-term saving. Even relatively modest early contributions can benefit from many years of potential investment growth.

There are limits and rules governing pension contributions; however, it is important to understand how they apply to both the person making the gift and the pension recipient. The most suitable approach will depend on your circumstances, objectives and wider estate.

Take advice before acting

The interaction between pensions, lifetime gifts, Inheritance Tax and retirement income can be complex. The rules are also changing, with further HM Revenue & Customs guidance and supporting material expected ahead of April 2027.

Rather than making large withdrawals or gifts simply because of the forthcoming changes, consider reviewing your overall financial position first. A coordinated approach could help you balance your financial security with your desire to pass more wealth to those you care about.

This article does not constitute tax, legal or financial advice and should not be relied upon as such. Estate and tax planning are not regulated by the financial conduct authority. For guidance, seek professional advice.

Decide who inherits

One of the main reasons for making a Will is the ability to decide who receives your money, property and possessions. You can also leave specific gifts, including sentimental items such as jewellery, family photographs, family heirlooms and other treasured belongings.

For unmarried couples and those not in a registered civil partnership, having a Will can be particularly important. The rules of intestacy do not generally provide the same automatic inheritance rights to unmarried partners as to spouses and registered civil partners, potentially leaving a surviving partner in financial uncertainty.

Protect your family

If you have children under 18, a Will allows you to nominate guardians to care for them if both parents die. You can also appoint executors to administer your estate and leave instructions for your preferred funeral arrangements.

Making a Will is also a time to review your wider financial arrangements. This may include reviewing life insurance, pension beneficiary nominations and other relevant protection policies, where appropriate, to ensure they remain suitable for your circumstances and to ensure they are written into an appropriate trust. Keeping these details up to date can make it easier for your loved ones to understand your arrangements.

Consider tax and charitable gifts

Inheritance Tax can be an important consideration when planning how wealth will be passed on. Depending on the value and structure of your estate, your beneficiaries may face a tax liability. Professional advice is essential to ensure you understand the available allowances, exemptions and potential planning opportunities.

You can also leave money to charities in your Will. In certain circumstances, leaving at least 10% of your net estate to charity can reduce the Inheritance Tax rate on some assets from 40% to 36%, while providing valuable support for a cause you care about.

Keep your Will up to date

Writing a Will isn’t a one-off exercise. It should be reviewed regularly and whenever your circumstances change, such as after marriage or divorce, the birth of a child or a significant change in your finances. You may also want to reconsider your wishes if any beneficiaries or executors are no longer suitable.

While a Will can provide valuable protection, it must be properly drafted and kept up to date to ensure it continues to reflect your wishes. Seeking professional advice will help you understand the options available and avoid potential complications.

This article does not constitute tax, legal or financial advice and should not be relied upon as such. Estate, tax planning and will writing are not regulated by the Financial Conduct Authority. For guidance, seek professional advice.

Why keeping records matters

When someone dies, executors may need to complete HM Revenue & Customs’ IHT400 form to report the estate’s value, alongside IHT403 to disclose relevant lifetime gifts. Without accurate records, completing the paperwork can be more difficult and may lead to delays or additional queries from HMRC.

Many people have also lost track of how much they have given. Just 31% of over-55s who have made a financial gift in the past seven years know the exact amount, while 45% can only provide a rough estimate and 24% have no idea.

Gifts can be worth more than expected

Among those who knew the exact amount or could estimate it, the average value of gifts over seven years was £42,056. A fifth (21%) had given £50,000 or more, highlighting why keeping detailed records can be particularly important.

Nearly half (48%) said they did not keep records because their gifts were not large enough to warrant keeping them, while 47% did not realise records were necessary. A further 21% relied on their memory.

What counts as a financial gift?

There is also widespread confusion about what constitutes a gift for IHT purposes. Three in five (59%) over-55s did not know that furniture, jewellery and antiques can count, while 55% were unaware that shares listed on the London Stock Exchange may also be included. Meanwhile, 32% were unaware that giving away a house, land or buildings can be relevant

Keeping a clear record of the amount, date, recipient and relationship can help executors provide the information required by HMRC. Records should be securely backed up and stored where the executor can access them.

Protecting loved ones from future stress

Gifting can provide valuable support to family and friends, but poor record-keeping can create unnecessary complications, potentially delaying probate and payments to beneficiaries. Allowances or exemptions may also be missed if gifts cannot be evidenced.

Keeping a clear, up-to-date record of gifts can give executors a clearer picture of an estate and help ensure the correct information is provided to HMRC. This can make the administration process smoother and reduce the risk of additional stress for loved ones at an already difficult time.

Source data:

[1] Research conducted by Canada Life among a nationally representative sample of 2,000 UK adults between 17–20 February 2026. The sample includes 998 adults aged 55 and over.

This article does not constitute tax, legal or financial advice and should not be relied upon as such. Estate and tax planning are not regulated by the Financial Conduct Authority. For guidance, seek professional advice.

The good news is that spotting a potential shortfall early gives you time to address it. Whether retirement is decades away or approaching quickly, asking yourself these five questions could help you take greater control of your financial future.

1. What does my dream retirement look like?

Start with the life you want to lead, not a pension figure. Do you dream of travelling more, spending time with family, taking up new hobbies or simply enjoying your days without financial worries?

Think about the costs involved, from essential household bills to holidays, leisure and support for loved ones. Your spending may also change over time, with higher expenditure in the early years before your priorities evolve.

2. Where will my income come from?

Your retirement income may need to come from several sources, including workplace and personal pensions, the State Pension, savings, investments or property. Knowing when each source becomes available is essential to building a sustainable income plan.

Check your State Pension forecast and National Insurance record, as gaps could affect your eventual entitlement. Understanding which income you can rely on can also help determine how much you need to generate from your private pension and other assets.

3. Am I saving enough?

Seeing a pension balance on a statement can be reassuring, but the figure alone does not tell you whether you are on track. What matters is how much income your savings could ultimately provide and whether it matches the life you want.

Consider your contributions, investment strategy, charges and the impact of inflation. If you discover a potential shortfall while you still have years before retirement, you have more time to increase contributions, review your investments or adjust your plans.

4. How will I turn savings into income?

Pension freedoms give you choices. You could use drawdown to take a flexible income while keeping your pension invested, buy an annuity to secure a guaranteed income, or combine approaches.

The decisions you make can have significant tax and investment implications. For example, taking large withdrawals in a single tax year could push you into a higher Income Tax band, while taking too much from drawdown could leave you with less money later in retirement.

5. What if life doesn’t go to plan?

A retirement plan based solely on everything going right can unravel quickly. Investment markets can fall, inflation can erode spending power and unexpected costs can arise. You may also live considerably longer than expected.

Professional financial advice will help you stress-test your plans against different scenarios and consider investment risk, tax, longevity and the most appropriate way to use your assets. Most importantly, it can help turn a collection of pensions and investments into a coherent plan for the life you want.

This article does not constitute tax, legal or financial advice and should not be relied upon as such. For guidance, seek professional advice. A pension is a long-term investment not normally accessible until age 55 (57 from April 2028, unless the plan has a protected pension age). The value of your investments (and any income from them) can go down as well as up, which would affect the level of pension benefits available. Investments can fall as well as rise in value, and you may receive back less than you invest.

Who can claim the credits?

Grandparents can qualify if they are over 16 but below State Pension age when providing care, and the child’s parent or main carer receives Child Benefit but does not need the associated National Insurance credit. The parent or main carer must agree to transfer the credit.

The rules are not limited to grandparents. Other eligible family members can also qualify, including great-grandparents, aunts, uncles and siblings, provided the relevant conditions are met. The credit is available for each week, or part-week, in which eligible care is provided.

How does the system work?

When someone claims Child Benefit for a child under 12, they normally receive a National Insurance credit. If they already have a qualifying year from work or other credits, they may be able to transfer that credit to an eligible family member who provides childcare.

There is only one credit available for each Child Benefit claim, regardless of how many children are included in that claim. However, if different children have different Child Benefit recipients, more than one credit could be transferred.

What could it mean for your State Pension?

National Insurance credits can help fill gaps in your record. Under the current system, the full new State Pension is £241.30 per week in 2026/27, though the amount you receive depends on your National Insurance history.

This means that claiming available credits could be particularly valuable for grandparents with gaps in their record, such as those who have reduced their working hours or stopped work to provide care. It is important to check your record first, as you should not apply if you already have a qualifying year for the period concerned.

How can you apply?

Applications are made using HMRC’s CA9176 form. You must wait until 31 October after the end of the tax year for which you are claiming, and both you and the Child Benefit recipient must provide the required information and declarations. Credits can be claimed retrospectively from 6 April 2011, provided the eligibility conditions are met.

Before applying, it is sensible to check your National Insurance record and ask the child’s parent or main carer to check theirs. This can establish whether a credit is available to transfer and whether doing so could improve your eventual State Pension entitlement.

Don’t miss out on valuable credits

Grandparents often provide invaluable support to their families, yet the financial implications of that care can easily be overlooked. National Insurance credits could offer a way to convert some of that unpaid childcare into additional State Pension entitlement.

This article does not constitute financial advice and should not be relied upon as such. For guidance, seek professional advice.

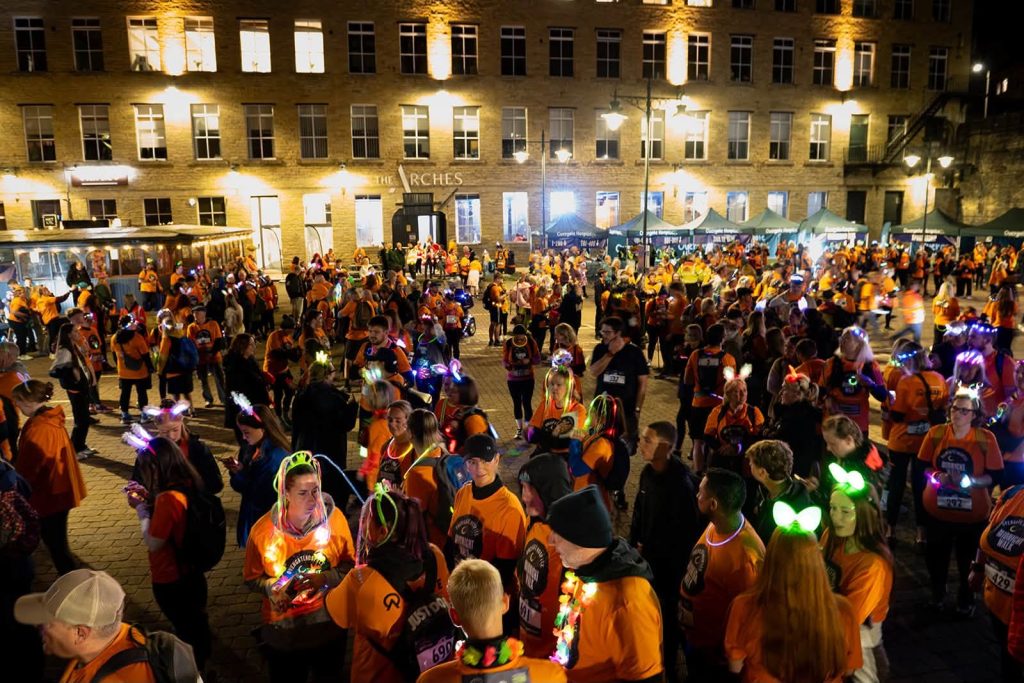
We did it! Toby and the team completed the 10-mile midnight challenge walk, raising £2,145 for Overgate Hospice who provides care for patients in Calderdale who have a terminal illness or a long term condition that cannot be cured.

The team smashed their 2025 amount of £1,260, reaching 140% of their target for this year’s target thanks to 77 much-valued supporters. We were also proud to sponsor the event’s mid-point checkpoint.

Although it was a late-night challenge, the route was filled with light and colour – with glowsticks and flashing headbands (not to mention some creative accessorising!) creating a fantastic celebratory atmosphere for the challenge.

The Hospice’s Midnight Walk sees thousands of walkers take on a 10-mile nighttime challenge for the hospice, which this year starts at Investing For Tomorrow’s base of operations, the iconic Dean Clough Mill, Halifax. 

Gifting rules leave many uncertain

Understanding how much can be gifted without triggering Inheritance Tax remains a challenge for many households. Just 15% of people feel confident about the amount they can give away each year without it being counted towards IHT, while 74% have either heard of gifting allowances and exemptions but do not know the details, or have no knowledge of them.

Only 26% of UK adults correctly identified the annual tax-free gift allowance as £3,000. Known as the ‘annual exemption’, it can be given to one person or split among several. Any unused allowance from the previous tax year can also be carried forward, provided the current tax year’s allowance is fully used.

Understanding the seven-year rule

More than half (57%) are either unaware of the seven-year rule or do not understand how it operates. Gifts not covered by an exemption can fall outside an estate for IHT purposes if the donor survives for seven years. If the donor dies sooner, the gift will use up some or all of the donor’s nil rate band. If the gift (alone or cumulatively) exceeds the nil rate band, tax on the excess will be payable by the gift recipient, with the full 40% rate potentially applying if death occurs within three years.

Only 27% say they fully understand the rule. For families considering gifting property or significant sums of money, getting the timing and tax treatment right can be crucial.

Planning is becoming more important

Rising property values, frozen IHT thresholds until 2031 and the inclusion of pensions in IHT calculations from April 2027 mean more families may need to reconsider their financial planning. Some households that never expected to pay IHT could find themselves affected.

Confusion can lead to missed allowances, unnecessary tax bills and added stress at an already difficult time. Understanding the rules early can give families a greater opportunity to make use of available exemptions, plan gifts carefully and ensure their assets are passed on as efficiently as possible.

Source data:

[1] Research conducted by Canada Life among a nationally representative sample of 2,000 UK adults between 17–20 February 2026

This article does not constitute tax, legal or financial advice and should not be relied upon as such. Inheritance Tax and tax planning are not regulated by the Financial Conduct Authority. For guidance, seek professional advice.